Understanding the Appraisal Process:
What is an Appraisal?
A Real Estate Appraisal is the result of a process of developing an opinion of value for real property, sometimes referred to as Land Valuation, Property Valuation, or Asset Valuation. We provide an unbiased estimate of what a buyer might expect to pay - or a seller receive - for a parcel of real estate, where both buyer and seller are informed parties.
The purchase of real property is a detailed transaction that requires many steps to complete. You are likely already familiar with some of the parties involved; Real Estate Agents are the face of the transaction, The Lender provides the loan necessary to fund the exchange, and the Title Company ensures that the title is clear to pass from buyer to seller. The Appraiser makes sure the value of the property is in line with the amount being paid.
How do I get an Appraisal?
In order to start the process, a bid request is sent to an Appraiser. This request should contain all of the following relevant information:
1. The location of the property, its physical address, as well as any unique amenities or complexities about the site. (i.e. Whether the property is in residential area vs. a rural location, if it is a waterfront property, on acreage, or if there is difficulty in reaching the property)
2. The type of property. There are different requirements for inspecting different properties, a Log Cabin out in the woods and a Duplex in town are going to be vastly different appraisals, design style and housing type is just as important to note as location, if not more so.
3. The reason for the appraisal. Are you looking for what the home could sell for today? Do you need a retroactive opinion of value for a divorce settlement or an estate valuation? Are you looking for a rent survey or an operating income statement alongside an appraisal?
4. Contact information, availability dates, and a desired date of completion. 5. Any other relevant property information is always welcome, information on updating or deferred maintenance are usually taken note of at the time of inspection, but information provided earlier in the process can help speed things like comparable research along earlier. Once a fee has been assigned, and the bid request has been accepted, our staff will contact you to schedule an appointment. Most inspections will only take around half an hour, but can take longer depending on the size and the complexity of the property.
Why do I need an inspection?
Most real estate transactions require an appraisal by the financial institution providing the loan, and when refinancing a home, your lender legally and contractually requires an appraisal to be done to verify the loan-to-value ratio. Note: Under Consumer Financial Protection Bureau Regulation 1002.14, Lenders are required to provide you with a copy of the appraisal or written valuation.
We inspect the property to ascertain its true status. We must see the aspects of the property firsthand, such as the number of bedrooms and bathrooms, the location of the property, the amenities, etc., to ensure they truly are present and in the shape a reasonable person would expect them to be in..
| 
|
| 
| Our inspection is not the same as a Home Inspection, although it shares similarities. While Home Inspectors look at the condition of the property for issues and needed repairs, we are analyzing other factors as well, such as location and the specific features that impact value. |
What happens during the inspection?
During the inspection, the appraiser will physically measure the building(s) to ensure the stated square footage is accurate, and can illustrate the layout of the home, as the inspection often requires creating a sketch of the floor plan. The appraiser identifies any obvious features - or defects - that would have an impact on the value of the property, including the quality of construction, and any updating that has been done to the property.
What is the Appraisal Process?
Following the inspection, multiple approaches are used to determine the value of real property:
A Sales Comparison, a Replacement Cost Calculation, and an Income Approach when rental properties are prevalent. These are often referred to as "The Three Approaches to Value".
• Approach #1: The Sales Comparison Approach:
Also called the Market Approach, the Sales Comparison Approach takes recent sales of similar properties in the subject’s area and compares them on a grid. Direct comparisons and valuation adjustments are made for items such as location, square footage, bedroom/bathroom count, amenities, and more. Comparing the subject to recently sold properties in the subject’s area, we adjust the comparable properties so that they more accurately match the features of subject property. For example, a comparable has a fireplace and the subject does not, the appraiser may subtract the value of a fireplace from the sales price of the comparable to equate it to the subject. In the inverse, if the subject has something such as an extra bathroom that a comparable does not have, the appraiser will add the value of that bath to the comparable property. Using knowledge of the value of certain items such as square footage, additional bathrooms, hardwood floor, fireplaces, or view lots (just to name a few), we adjust the comparable properties so that they more accurately match the features of the subject property on the Sales Comparison Grid.
SALES COMPARISON GRID EXAMPLE: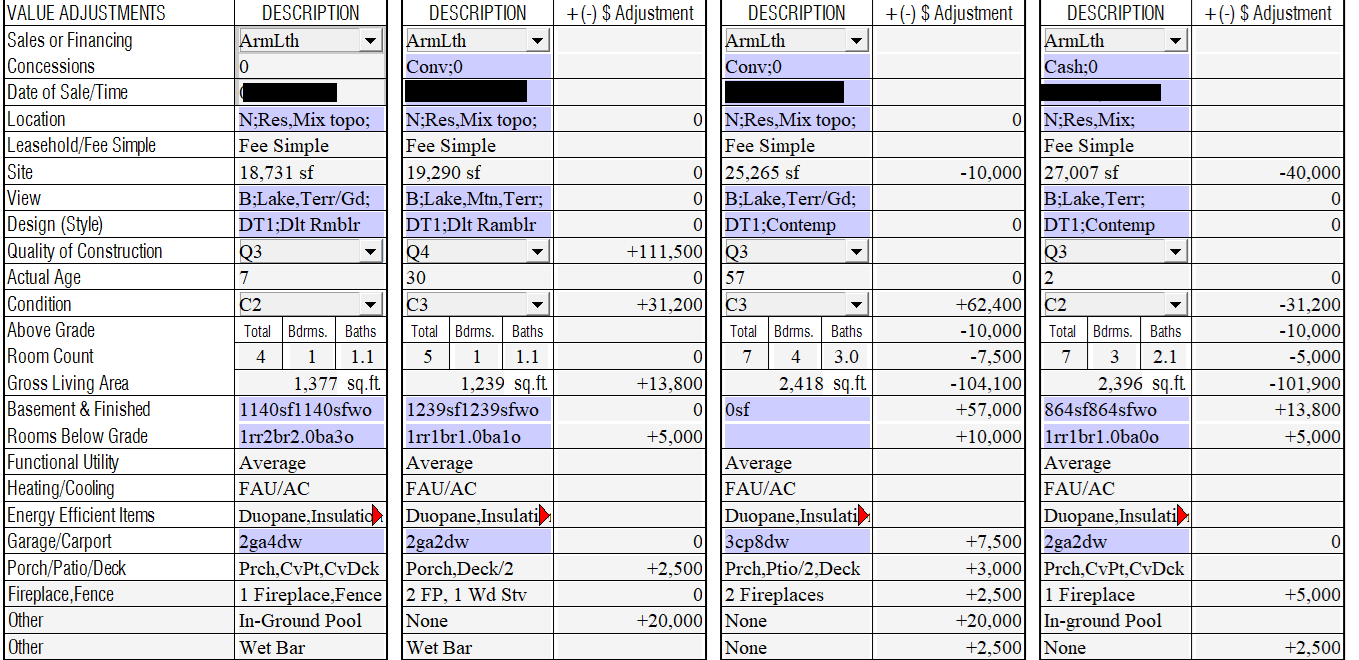
|
|
|
| The Sales Comparison Approach provides the most reliable support for market value and is typically awarded the most importance when the appraisal is for a home purchase. |
• Approach #2: The Cost Approach
The Cost Approach is the estimated reproduction or replacement cost of a property. Taking into account the estimated value of the site, plus the depreciated cost of the building, and any other improvements. Here we gather information on local building costs, labor rates, and other factors to determine how much it would cost to construct a property comparable to the one being appraised. This value usually sets the upper limit on what a property would sell for. The cost approach is generally the least used method, but it remains an important approach to value.
• Approach #3: The Income Approach
The third way of valuing a property is sometimes applied when a neighborhood has a reasonable number of rental properties. In this scenario, the amount of revenue the real estate produces is factored in with other rents in the area for comparable properties to derive the current value.What does this mean for me?
Combining information from all applicable approaches, the appraiser is then ready to state an estimated market value for the property at hand. While the appraised value is probably the most accurate indication of what a property would sell for in an open market, it may not be the price at which the property closes. Depending on the specific circumstances of the buyer or seller, their level of urgency or a buyer's desire for that exact property, the closing price of a home can always be driven up or down. The appraised value is typically employed as a guideline for lenders who don't want to loan a buyer more money than the property would likely sell for in an open marketplace. NCW Appraisal will guarantee you get the most fair and balanced property value, so you can make the most informed real estate decisions. Whether you are in Chelan, Douglas, Grant, Okanogan, or even Kittitas county, when it comes to knowing the true value of homes features, NCW Appraisal is your local authority.